Things to Understand About Venezuela's Oil and Gas Sector Before You Consider Investing
This guide is different from the rest of our real estate-focused series. If you've come to Venezuela Advisor primarily for property guidance, treat this as background context — the energy sector explains a great deal about the country's broader investment climate, but it operates under an entirely different risk profile than buying an apartment in Altamira or Las Mercedes. We're including it in this series because clients evaluating real estate almost always ask about the oil sector at some point in the conversation, and we'd rather answer that question directly and honestly here than leave it unaddressed.

What doesn't change: the geology
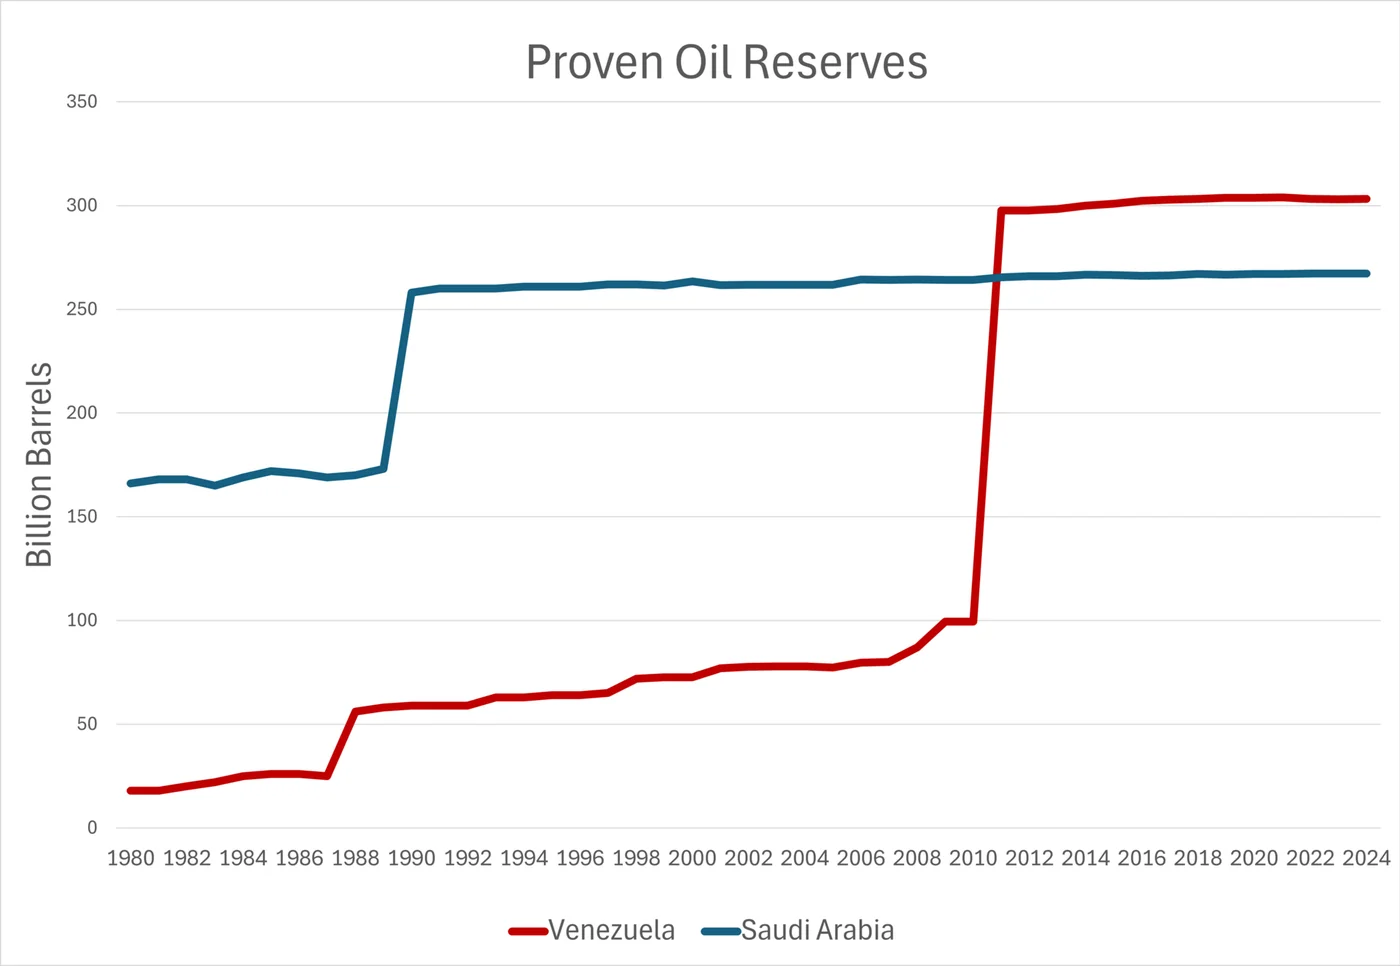
This is one of the few facts in this guide we can state without any reservation, because it's a geological fact documented by a recognized international body: Venezuela holds the world's largest proven oil reserves, according to figures published by OPEC, ahead of Saudi Arabia and Iran. That fact doesn't depend on any government, any sanctions regime, or any political cycle — it's the geological foundation underneath any long-term thesis about Venezuela's energy sector. It's worth being precise about what this fact does and doesn't tell you. It tells you the resource exists in the ground in enormous quantity. It tells you nothing, on its own, about how much of that resource can be profitably extracted under current infrastructure conditions, at what cost, under what legal terms, or on what timeline. Those four questions are where the real investment analysis actually lives, and they're addressed — separately and deliberately — in the sections that follow. The U.S. Energy Information Administration country analysis provides a separate reserve and production reference.

What changes fast: the regulatory regime
This is precisely the gap between stable geological potential and variable real investment opportunity that any serious analysis of this sector must acknowledge explicitly, rather than presenting potential as if it guaranteed immediate return. We're intentionally not naming specific companies, specific licenses, or specific dates in this section — not because that information doesn't matter, but because it changes fast enough that anything we wrote today could be inaccurate by the time you're reading this. That volatility is itself the lesson: treat any third-party claim about "the current rules" with the same skepticism you'd apply to a claim about tomorrow's weather six months out. Current activity should be checked against OFAC's Venezuela-related sanctions page, not a static summary.

The less-discussed problem: infrastructure
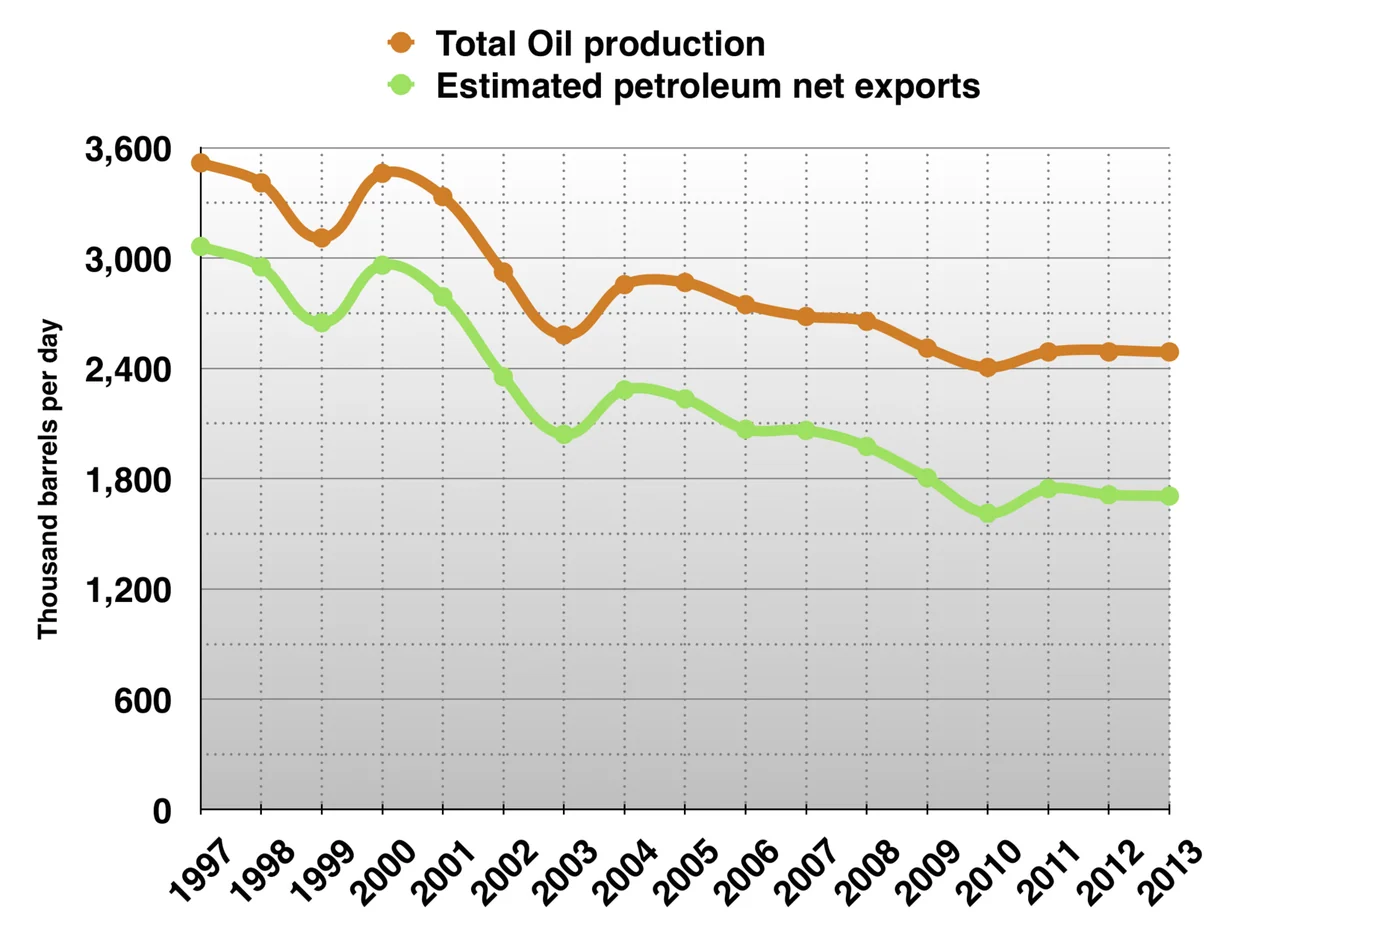
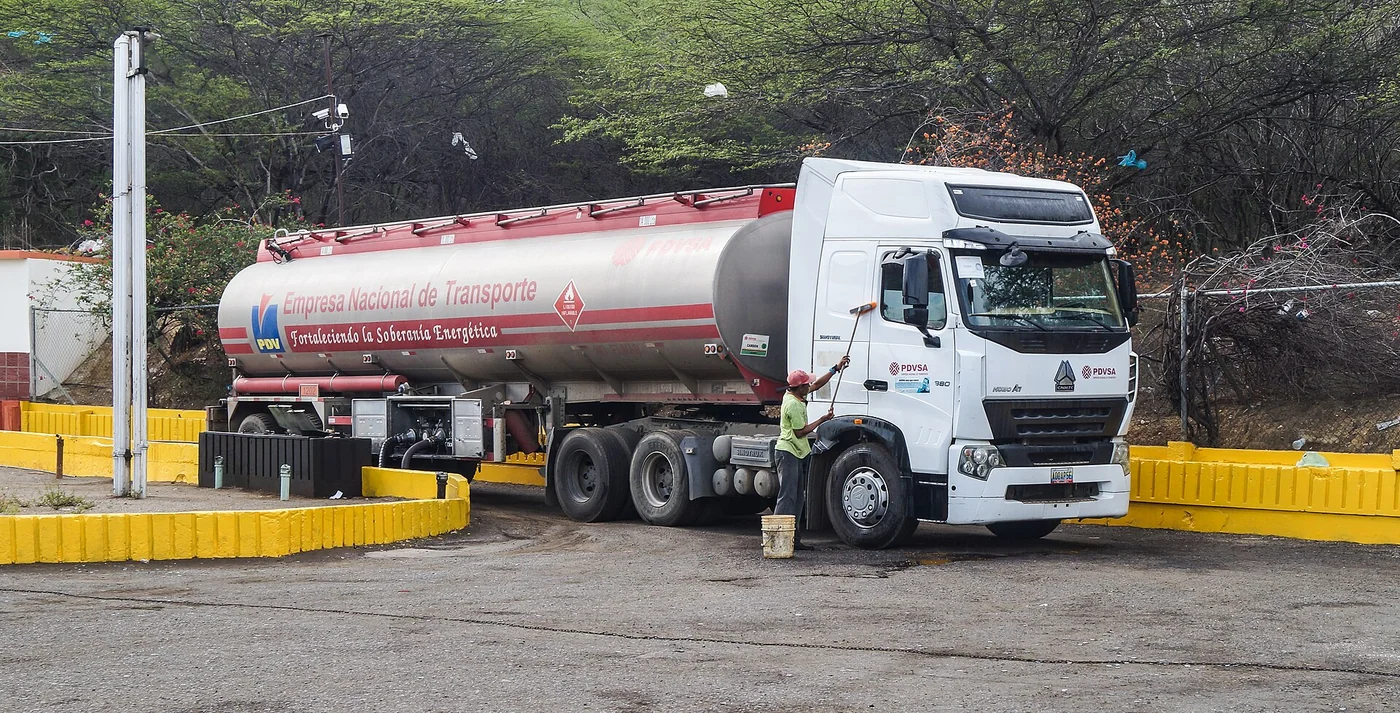
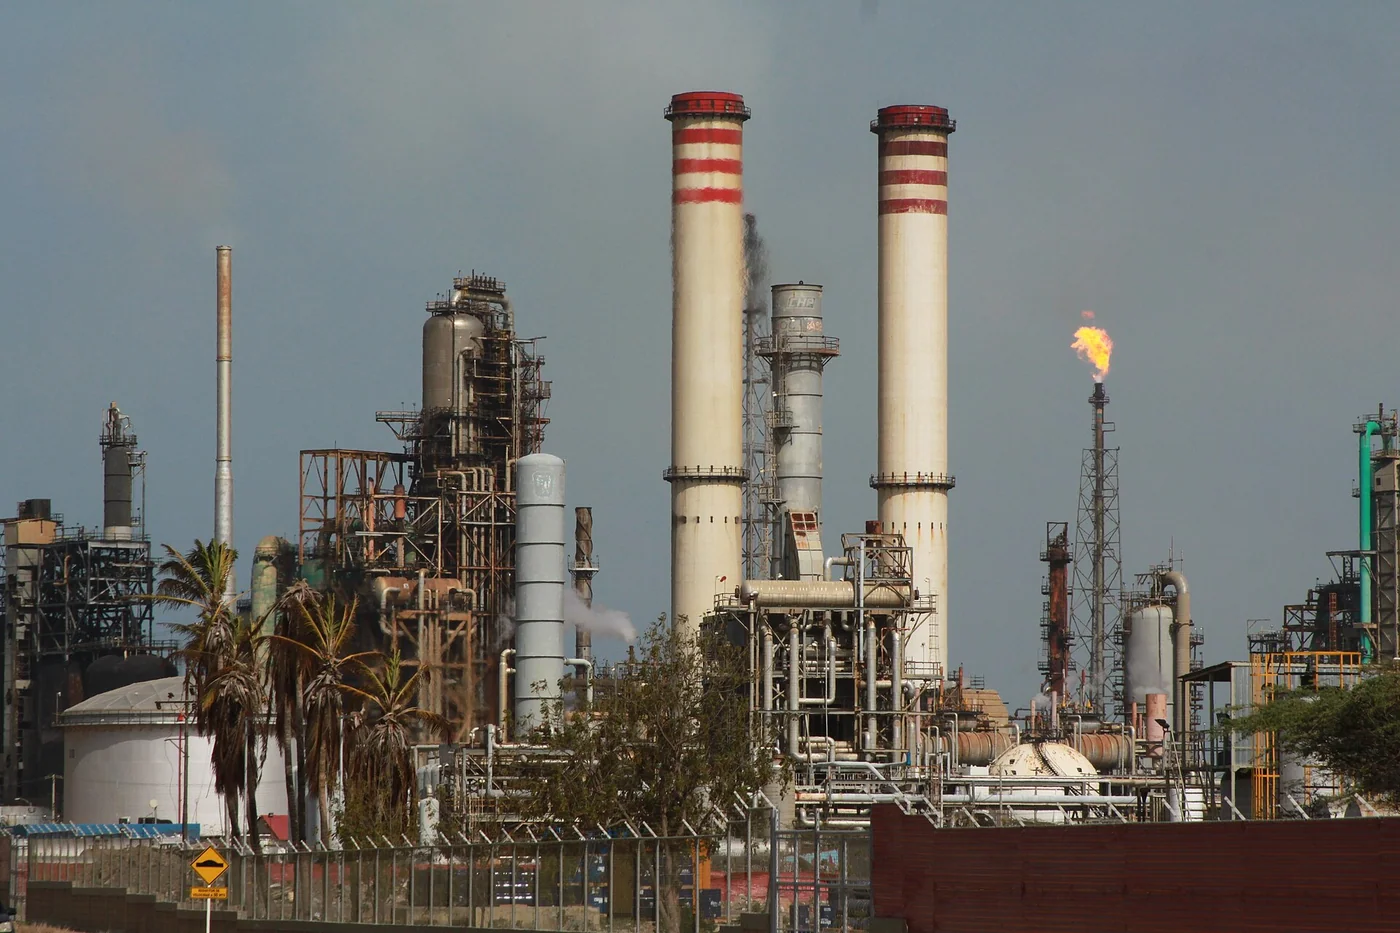
Beyond the regulatory framework, any serious evaluation of this sector must consider the physical condition of refineries, pipelines, and export terminals, which went through years of underinvestment in maintenance. The speed of any production recovery depends on both physical infrastructure and the legal framework that enables it — two independent variables that must be evaluated separately. This distinction matters because the two variables can move in opposite directions. A regulatory environment could theoretically open up faster than the physical infrastructure can support increased production, meaning that legal access to the sector doesn't automatically translate into operational capacity on any predictable timeline. Any investment thesis that assumes regulatory change alone will unlock production is skipping an entire category of real-world constraint. Reuters' sector briefing likewise describes the gap between Venezuela's reserve base and operating capacity.

Natural gas: the quieter opportunity
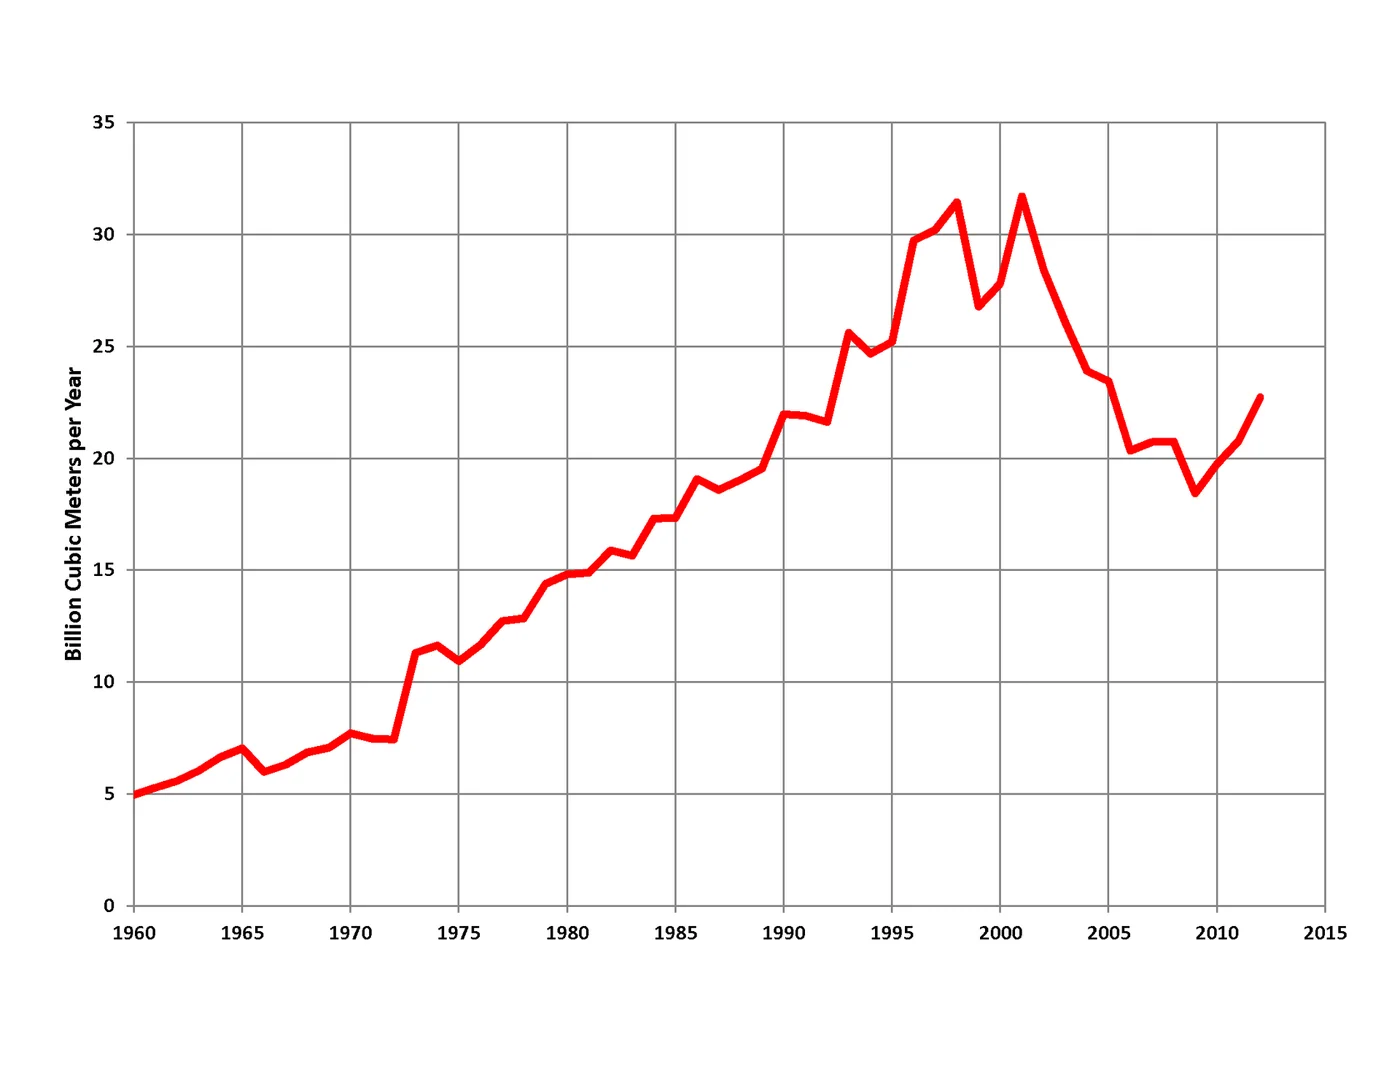
Venezuela also holds significant natural gas reserves, a resource that receives far less media attention than oil but has direct, urgent applications in power generation and petrochemicals — two sectors the country needs to reactivate regardless of what happens with crude oil specifically. Gas projects also tend to carry a somewhat different regulatory profile than crude oil exports, in part because a larger share of gas production is typically directed toward domestic power generation rather than international export markets. That domestic orientation can mean different licensing considerations apply, though — consistent with the caution running through this entire guide — the specific current terms should be confirmed with specialized counsel rather than assumed from general principles. The Congressional Research Service's Venezuela natural-gas report discusses the reserve base, domestic use, licensing and pipeline requirements.

Who this sector actually fits
Honestly: this is not a sector for the average individual investor reading this guide to decide whether to buy an apartment in Caracas. It requires significant capital, specialized legal advice in energy and international sanctions law, and a multi-year horizon. It makes sense primarily for specialized funds, oil services companies with prior regional experience, or institutional investors with an explicitly high risk appetite. If you recognize yourself in that description, the right next step isn't reading a general blog guide like this one — it's engaging directly with counsel who specializes in OFAC compliance and Venezuelan energy law specifically, before any capital commitment of any size. If you don't recognize yourself in that description, that's a useful signal in itself: this sector, whatever its long-term potential, is very likely not the right vehicle for your specific situation, and that's a perfectly reasonable conclusion to reach after reading a single guide rather than after losing capital in the sector directly. The sanctions-compliance part of that advice should be grounded in OFAC's own licensing materials.

Due diligence questions before any capital moves
- What specific license, if any, currently authorizes the activity you're considering?
- Who is the counterparty, and what is their track record operating under sanctions-adjacent conditions elsewhere?
- What happens to your position if the license is revoked or the sanctions regime tightens with no notice?
- Does your own country's law impose separate restrictions on this kind of participation, independent of U.S. sanctions?
- Is there a clear, contractually defined exit mechanism if the regulatory environment shifts against you mid-investment?
- Has independent legal counsel — not the counterparty's own lawyers — reviewed the specific structure being proposed?
- What is the realistic, infrastructure-adjusted timeline to first cash flow, as distinct from the licensing timeline alone?
Notice that none of these seven questions can be answered by reading a pitch deck or a promotional presentation. Every one of them requires independent verification, and a counterparty unwilling or unable to support that verification process is, on its own, a disqualifying signal regardless of how attractive the underlying opportunity sounds. For U.S. sanctions questions, the relevant starting point is OFAC's Venezuela program page.

Common mistakes uninformed investors make
Treating geological potential as investment certainty
The size of the reserves says nothing about near-term extractable value under the current regulatory and infrastructure constraints. Confusing the two is the single most common analytical error we see, and it's an easy one to make precisely because the reserve figures are so genuinely impressive on their own.

Skipping specialized sanctions counsel
General corporate counsel, however competent, is rarely sufficient here. This sector specifically requires lawyers who track OFAC guidance in real time.

Assuming today's rules will hold for the life of the investment
As described above, this regulatory environment has changed multiple times in recent years. Any multi-year projection that assumes static rules is, by definition, incomplete.

Confusing "sanctions relief" headlines with a fully open market
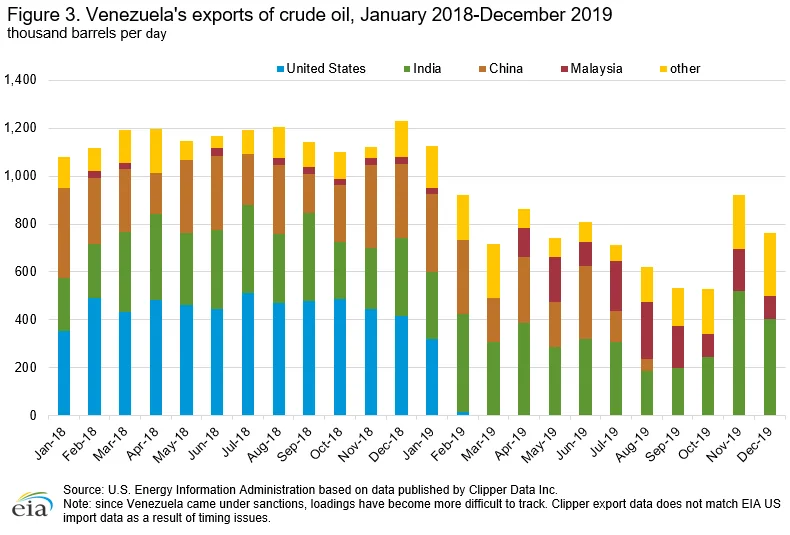
Even during periods of eased restrictions, specific licenses have historically applied to specific companies, specific transactions, or specific time windows — not a blanket reopening. Reading a headline about relief and assuming general access is available is a costly misreading we've seen repeated across market cycles.

Underestimating the timeline to actual cash flow
Even under favorable licensing conditions, the gap between securing legal access and generating actual, distributable cash flow can run into years given the infrastructure constraints described above. Investors who model returns on a licensing timeline alone, without adding the infrastructure ramp-up separately, consistently overestimate how quickly capital could be returned to them.

A brief, honest history of the sector's volatility
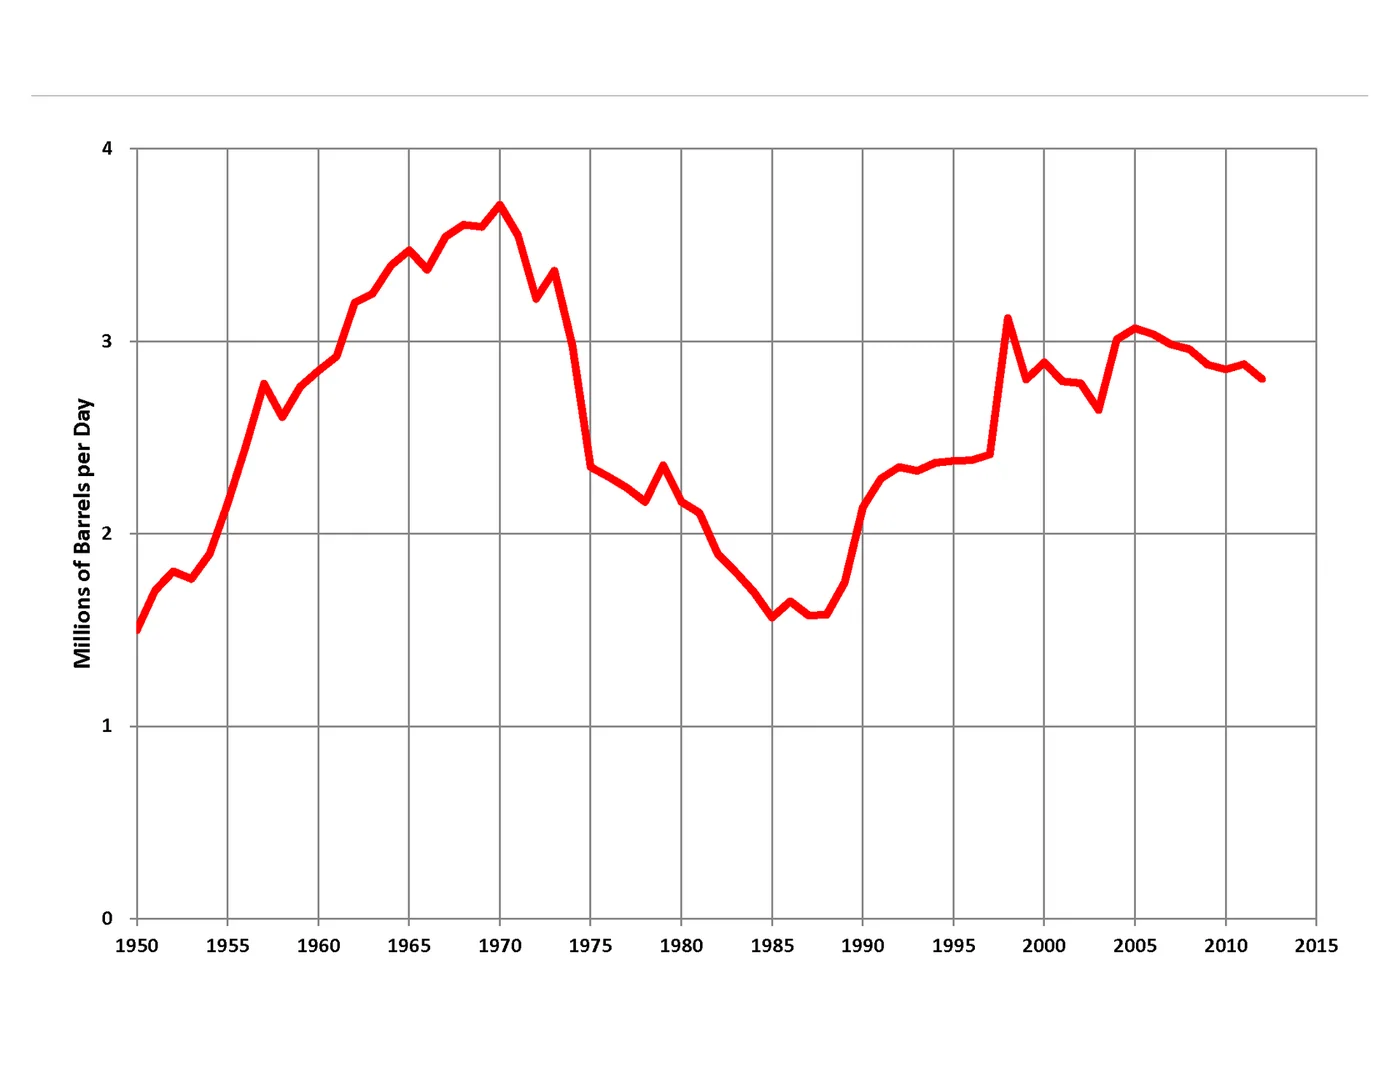
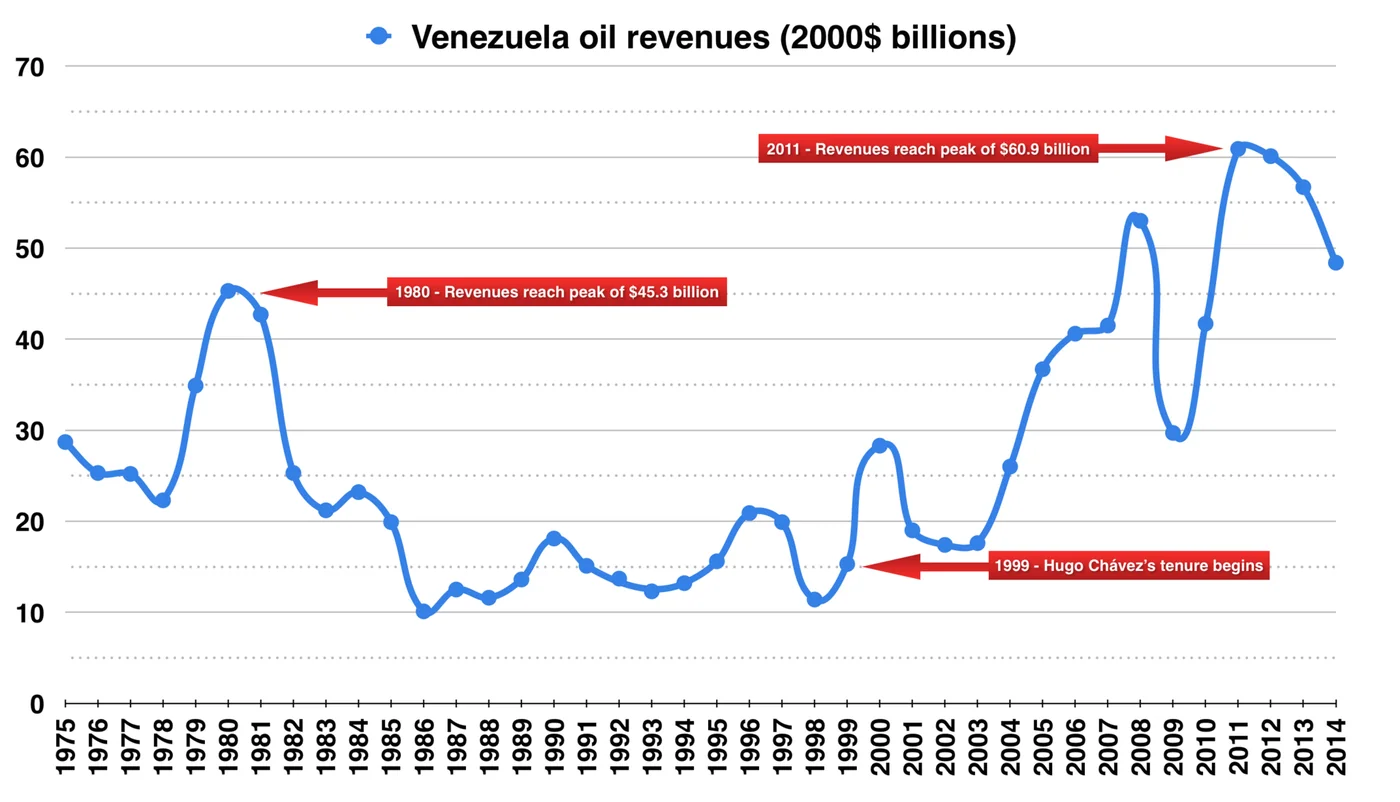
Venezuela's oil industry has moved through several distinct regulatory eras over the past few decades: a period of predominantly private and joint-venture operation, a wave of nationalization that consolidated control under the state oil company, and more recently a period shaped heavily by international sanctions and periodic, narrowly scoped licenses for specific foreign operators. Each transition reshaped who could participate, on what terms, and with what legal protections. We mention this history not to draw a specific conclusion about what comes next — that would be exactly the kind of prediction we're avoiding in this guide — but to illustrate a pattern: this sector's rules have never stayed fixed for long, and any investor evaluating an opportunity here should build that expectation into their planning from day one, rather than treating the current regulatory snapshot as a stable baseline. Reuters' historical sector summary describes the nationalization, joint-venture and sanctions sequence in similar terms.

This pattern isn't unique to Venezuela, but the degree of regulatory swing here has been more pronounced than in most oil-producing nations over the same period, which is exactly why generic country-risk models built for more stable jurisdictions tend to understate the real variance an investor should plan for. The legal layer is documented in OFAC's archive of Venezuela authorities and licenses.

How this compares to other national oil companies in the region
Venezuela is not unique in having a state oil company that dominates the sector — Mexico's Pemex and Brazil's Petrobras are structurally similar in that regard. What distinguishes Venezuela's case is the degree and duration of the specific external sanctions regime layered on top of that state-dominated structure, which has no close parallel among its regional peers over the same time period. This is one more reason generic "emerging market energy sector" analysis doesn't transfer cleanly to the Venezuelan case without significant adjustment. The comparison should still be read alongside the specific Venezuela sanctions framework, rather than a generic emerging-market label.

An investor with prior experience evaluating Pemex or Petrobras opportunities should resist the instinct to apply that same mental model directly to Venezuela. The state-dominance structure looks similar on paper; the layered sanctions and licensing complexity underneath it does not, and that difference changes almost every practical aspect of how a transaction actually gets structured and executed.

Three illustrative scenarios, clearly labeled as such
To make the abstract discussion above more concrete, consider three illustrative — not predictive — scenarios for how the regulatory environment could evolve, and what each would mean in practice for the categories of investor described in this guide.

Scenario A: Continued narrow, case-by-case licensing
Under this scenario, specific operators continue receiving specific, time-limited authorizations, with no broad market opening. This favors incumbents who already hold active licenses and relationships, and offers little practical entry point for a new investor without an existing foothold.

Scenario B: Broader sectoral relief with conditions
Under this scenario, restrictions ease for defined categories of activity — for instance, certain gas projects oriented toward domestic power generation — while crude oil export activity remains more tightly restricted. This would meaningfully change the relative attractiveness of the gas opportunities described earlier in this guide.

Scenario C: Renewed tightening
Under this scenario, existing licenses are narrowed or revoked, and the operating environment becomes more restrictive than today. Any investor whose thesis depends on continued or expanding access should have a clearly defined response plan for this scenario specifically, not just for the more optimistic ones.

We present these three deliberately without a probability attached to each, because assigning confident probabilities to geopolitical and regulatory outcomes is exactly the kind of false precision this guide has tried to avoid throughout. The value of the exercise isn't predicting which scenario occurs — it's confirming, before you commit capital, that your specific investment structure survives all three without catastrophic loss. An investment that only makes sense under the single most optimistic scenario is, by definition, a speculative bet on that scenario materializing, not a diversified investment thesis.

Glossary
OFAC: the U.S. Treasury's Office of Foreign Assets Control, which administers U.S. sanctions programs.
Proven reserves: the portion of a resource that can be extracted profitably under current economic and technological conditions with a high degree of certainty.
Petrochemicals: industrial chemical products derived from petroleum or natural gas, a major downstream use for Venezuela's gas reserves.
Force majeure: a contract clause addressing extraordinary events — including regulatory shocks — outside either party's control, worth reviewing closely in any energy-sector agreement here.

Key takeaways
- Venezuela's geological oil potential is a documented, stable fact, independent of the short-term political cycle.
- The sanctions and licensing framework is the fastest-changing variable and must always be verified against the most current source available, never assumed.
- This is a high-barrier-to-entry sector, not recommended for the individual investor without highly specialized advisory.
- Natural gas offers a lower-profile but genuinely significant opportunity within the same broader sector.
- Physical infrastructure constraints and regulatory constraints are separate variables — resolving one doesn't automatically resolve the other.
If your interest lies in Venezuela's broader investment climate rather than energy specifically, our Caracas real estate guide is a far more accessible starting point for most readers of this site — one where the risk profile, documentation requirements, and realistic timelines are considerably more predictable than anything described in this guide.

Discuss your plans
Use the contact page to send a message about your circumstances.
Contact an advisorQuestions or comments?
Leave us your message through the contact form — we will be glad to share our experience and help you with the next steps of your plans in Venezuela.
- OPEC — Venezuela profile — Reserve and OPEC-member context.
- U.S. Energy Information Administration — Venezuela country analysis — Reserve, production and country energy reference.
- U.S. Treasury OFAC — Venezuela-related sanctions — Licensing, general-license and legal-authority context.
- Congressional Research Service — Venezuela’s Natural Gas: Opportunity Knocks? — Natural-gas reserves, production, licensing and pipeline context.
- Reuters — Venezuela oil and mining sectors: large potential, weak output — Reported reserve, production, nationalization and infrastructure context.
This guide is general orientation, not a guarantee of eligibility, safety or investment returns. For the scope of the October 2026 priority update, read our editorial policy.