Private Healthcare and Insurance in Venezuela: A Practical, City-Specific Guide (2026)
Healthcare access is one of the factors families weigh most heavily when relocating, as noted in our cost of living guide. This guide looks specifically at how private healthcare and insurance actually work across Venezuela's main cities today, and what a family or individual should confirm before assuming a given city or plan meets their actual needs. The WHO Health Cluster describes access to health care in Venezuela as constrained, so local verification matters.

Specialist access varies sharply by city
What to confirm before you rely on a clinic or policy: Pair this with the cost-of-living comparison when modeling a move. The U.S. Department of State health guidance likewise advises checking coverage, payment and facility arrangements before care is needed.

- Which hospitals/clinics your insurer actually pays (network lists change)
- Cash-pay price ranges for common procedures if you are out-of-network
- Availability of your required specialties in the city where you will live
- Emergency protocols and transport time from your neighborhood
- Whether your existing international policy covers Venezuela adequately or needs a rider
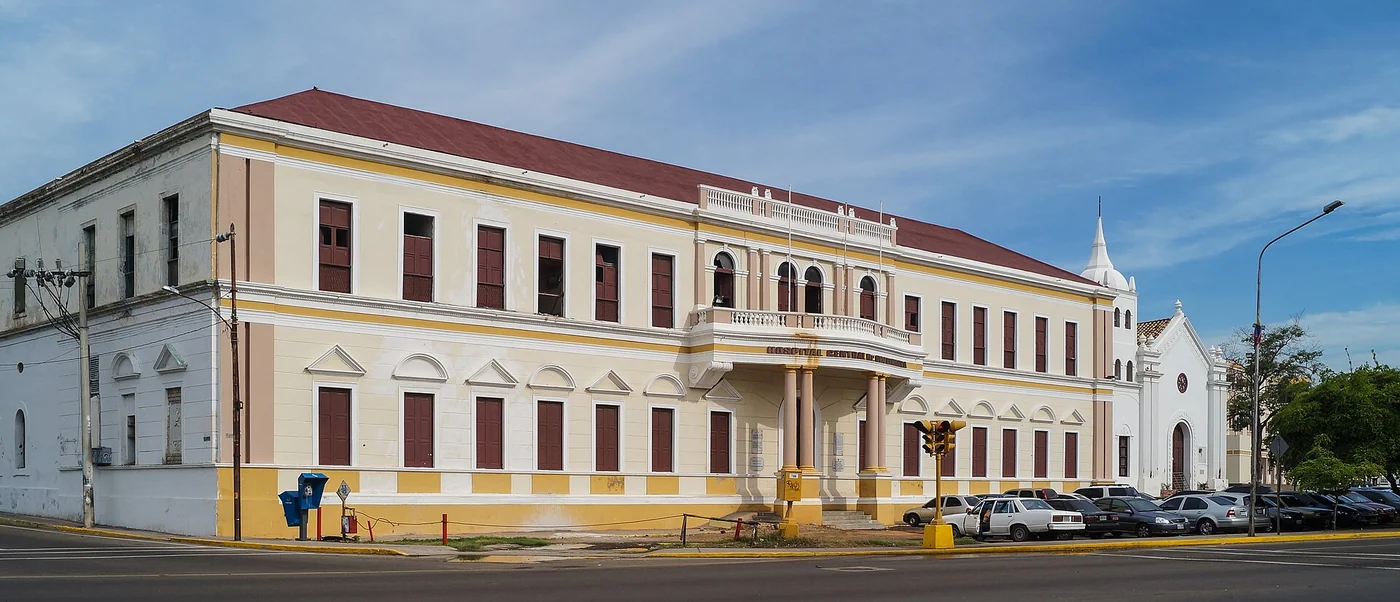
Illustrative index, not a formal survey: Caracas offers by far the deepest network of private specialists, reflecting the same demand concentration described throughout this guide series, particularly in the eastern municipalities where international demand is strongest. This concentration means a family's choice of city carries real healthcare consequences beyond the general cost-of-living differences described in our cost comparison guide. A family with an ongoing or anticipated specialist need should weight this factor heavily, since the theoretical savings from living in a lower-cost city can be outweighed entirely by the practical cost and disruption of regularly traveling to Caracas for care not available locally on short notice. The Department of State distinguishes adequate facilities in Caracas and other major cities from harder-to-find care in rural areas.

Private insurance vs. paying out of pocket: a genuine tradeoff
Neither approach is universally correct — it depends on your risk tolerance, your health history, and how predictable you need your monthly costs to be. Younger, healthier individuals with limited savings sometimes reasonably choose to pay out of pocket for routine care while accepting the risk of a larger unplanned expense down the road, whereas families with children, older members, or known health conditions generally find the predictability of insurance premiums worth the ongoing cost month after month. Neither choice is inherently wiser — it's a genuine tradeoff between predictable recurring cost and variable but potentially lower total spending, and the right answer depends entirely on your specific household's health profile and financial cushion at this point in time. It is also important to remember that medical care is not free in Venezuela and many providers expect cash or up-front payment.

What different levels of care actually cost in practice
Request a written quotation from the actual clinic and ask the insurer about provider networks, exclusions, deductibles, emergency authorization and payment arrangements. A generic dollar price cannot establish what a particular appointment, procedure or emergency will cost. Confirm the provider network, exclusions, deductibles and payment process in writing; a generic dollar figure cannot establish a particular clinic's price.

Choosing a private insurance plan carefully
Confirming which specific clinics and hospitals a plan's network actually includes, rather than assuming broad coverage based on a general brand reputation, avoids the unpleasant discovery that your preferred provider isn't included at the moment you need care most and have the least patience for administrative surprises. Beyond the network question, most plans include annual coverage caps and specific exclusions — pre-existing conditions, certain procedures, waiting periods for particular treatments — that materially affect what the plan actually covers in practice versus what its marketing materials suggest at first glance. Requesting the full policy document, not just a summary brochure, and reading the exclusions section specifically before signing avoids discovering a critical gap only when you attempt to file a claim and it's too late to switch to a better-suited plan. The cheapest available premium sometimes comes with correspondingly narrow coverage, a smaller network, or higher out-of-pocket requirements per visit that erode the apparent savings once actually used. Comparing plans holistically — premium, network breadth, coverage caps, and exclusions together — produces a more accurate sense of real value than ranking plans by premium price alone, which can be genuinely misleading in either direction depending on how a family's specific needs align with each plan's particular strengths and gaps.

Planning ahead for a genuine emergency
Knowing in advance which hospital you'd go to for a genuine emergency, and confirming that facility accepts your specific insurance or has a clear cash-payment process, removes a critical decision from the moment when you're least equipped to research it calmly and under pressure. Beyond simply knowing which hospital to go to, keeping insurance policy numbers, emergency contacts, and any relevant medical history physically accessible — not just stored on a phone that might be lost, damaged, or uncharged in an actual emergency situation — provides a practical backup that costs nothing to prepare and can matter significantly if the worst happens at the least convenient moment. A simple printed card kept in a wallet or bag, updated periodically as circumstances change, serves this purpose well. Some private facilities require upfront payment or a deposit before treatment, even for emergencies, which can create a genuinely stressful situation if the necessary funds aren't immediately accessible when they're needed most. Confirming a specific facility's payment policy in advance, and maintaining accessible emergency funds separate from your regular budget, addresses this risk before it becomes an urgent problem during an already difficult and disorienting moment for the whole family. The State Department warns that ambulance availability and response time can be unreliable and that some private facilities require up-front payment, so this plan should be confirmed before an emergency.

Mistakes we consistently see people make
Assuming insurance coverage without confirming the specific network, underestimating the cost gap between routine and emergency care, and failing to identify a go-to hospital before an emergency arises are the three mistakes we see most consistently across the families and individuals we've worked with on this topic. Employees who receive health insurance as an employment benefit sometimes never review the actual policy details, assuming the coverage their employer selected is automatically adequate for their family's specific needs and circumstances. Reviewing the network, caps, and exclusions of an employer-provided plan with the same scrutiny applied to a self-purchased policy — and supplementing it independently if genuine gaps exist — protects against discovering an inadequate default only when a claim is actually needed and it's already too late to adjust.

Delaying preventive care due to short-term cost concerns
Some individuals, particularly those paying out of pocket, delay routine preventive care to save money in the short term, only to face a more serious and more expensive condition later that earlier intervention could have caught or prevented entirely. Budgeting for regular preventive visits as a fixed, non-negotiable expense — rather than an optional cost to skip when money is tight — tends to reduce total healthcare spending over time, not increase it, precisely because early detection is almost always cheaper to address than a condition allowed to progress unmonitored.

Glossary
Network: the specific set of clinics, hospitals, and doctors a given insurance plan actually covers, distinct from general marketing claims about broad or comprehensive coverage.
Out-of-pocket: paying directly for care without insurance, common for routine visits even among the insured, particularly when a visit falls below the plan's stated deductible amount.
Coverage cap: the maximum amount an insurance plan will pay toward a claim or over a policy period, after which the policyholder bears any remaining costs directly out of pocket.
Pre-existing condition: a health condition that existed before a policy's start date, often subject to specific exclusions or extended waiting periods under many private plans.
Deductible: the amount a policyholder must pay out of pocket before insurance coverage begins to apply to a given claim or policy period, varying by plan.
Rider: an optional add-on to a base insurance policy that extends coverage to a specific area, such as dental or vision care, not included in the standard base plan by default. Beyond clinical care itself, medication availability and cost represent a meaningful and sometimes overlooked part of healthcare planning, particularly for anyone managing an ongoing condition requiring regular prescriptions over an extended period. Availability and pricing for specific medications can vary by pharmacy and by city, and confirming reliable access to any medication you depend on regularly — before relying on it being available exactly when needed — is worth doing as part of the same due diligence recommended for insurance and provider selection throughout this guide. For temperature-sensitive products, UNICEF's Venezuela cold-chain account explains why storage temperatures and monitoring matter; do not infer that a pharmacy follows those practices without asking.

Medication access and cost planning for ongoing prescription needs
For medications requiring cold storage or specific handling, confirming the pharmacy's actual storage practices, not just its general reputation, matters for medication efficacy in ways that aren't always obvious to a patient without a pharmacy or clinical background. This is a reasonable question to ask directly, particularly for anyone dependent on a medication where quality control genuinely matters clinically and where a lapse could have real health consequences.

The growing and genuinely useful role of telemedicine in Venezuela today
Telemedicine is a useful option where a Venezuelan or overseas provider actually offers it, including a genuinely useful option for routine consultations, prescription renewals, and follow-up care that doesn't require an in-person physical examination to be effective. This can be particularly valuable for returning diaspora members and foreign residents who've maintained relationships with specialists abroad and want to continue some level of continuity of care during a transition period, without needing to establish an entirely new provider relationship from scratch immediately. That said, telemedicine has real limits — it's not a substitute for in-person examination when a condition genuinely requires hands-on assessment, and confirming which situations warrant an in-person visit versus a remote consultation is a conversation worth having directly with your chosen provider rather than assuming telemedicine can substitute for all care needs indefinitely without any tradeoffs at all. PAHO's telehealth program materials provide implementation guidance, but they are not a directory of Venezuelan providers.

Mental health care access and shifting stigma considerations over time
Mental-health access is uneven: the WHO Health Cluster lists mental health and psychosocial support among Venezuela's 2026 health priorities, while the U.S. State Department cautions that psychological and psychiatric services are limited. Confirming a specific provider's approach, credentials, and any language considerations — particularly relevant for foreign residents seeking care in their native language — deserves the same direct verification recommended throughout this guide for physical healthcare providers. General reassurances about "mental health support being available" are less useful than confirming a specific, credentialed provider who's actually a good fit for the particular need at hand and the specific therapeutic approach a family or individual is looking for.

Dental and vision care as genuinely separate insurance considerations
Dental and vision care often fall outside standard health insurance coverage or require separate supplemental policies, a distinction worth confirming explicitly rather than assuming these are automatically included in general health coverage without checking directly. Families with anticipated orthodontic needs for children, in particular, should research this specifically well in advance, since these costs can be substantial and are easy to overlook when focused primarily on general medical coverage during the initial insurance selection process at the start of a move. Vision care, similarly, sometimes requires a separate rider or entirely separate policy for anything beyond a basic routine exam, and confirming this in advance — particularly for anyone who wears corrective lenses or has a family history of vision issues — avoids an unexpected out-of-pocket expense down the line for something that could have been anticipated and planned for from the outset of the insurance selection process.

Key takeaways and how to proceed
- Specialist access is heavily concentrated in Caracas relative to other major cities, a factor worth weighing in any relocation decision.
- Insurance and out-of-pocket payment each make sense for different risk profiles and needs — there's no universally correct choice for every household.
- The cost gap between routine and emergency care is substantial and worth planning for explicitly in advance, not discovering during an actual crisis.
- Identify a go-to hospital and confirm network coverage before an emergency happens, not during one when time and clarity are both limited.
- Review employer-provided coverage with the same scrutiny as a self-purchased policy — don't assume it's automatically adequate.
- Confirm reliable access to any medication you depend on regularly, including proper storage practices at the specific pharmacy you'll use.
If you're planning a move to Venezuela, we can help you think through healthcare access and insurance options for your specific situation, family composition, and any ongoing medical needs you may already have.

Discuss your plans
Use the contact page to send a message about your circumstances.
Contact an advisorQuestions or comments?
Leave us your message through the contact form — we will be glad to share our experience and help you with the next steps of your plans in Venezuela.
References
- U.S. Department of State, Venezuela travel advisory — medical care, payments and emergency planning
- WHO Results Report 2024–2025: Venezuela country profile
- WHO Health Cluster: Venezuela (Bolivarian Republic of)
- UNICEF Venezuela: Well-preserved vaccines to ensure their effectiveness
- PAHO: Telehealth Program Documents
This guide is general orientation, not a guarantee of eligibility, safety or investment returns. For the scope of the October 2026 priority update, read our editorial policy.